Holiday Rental Insurance in the USA
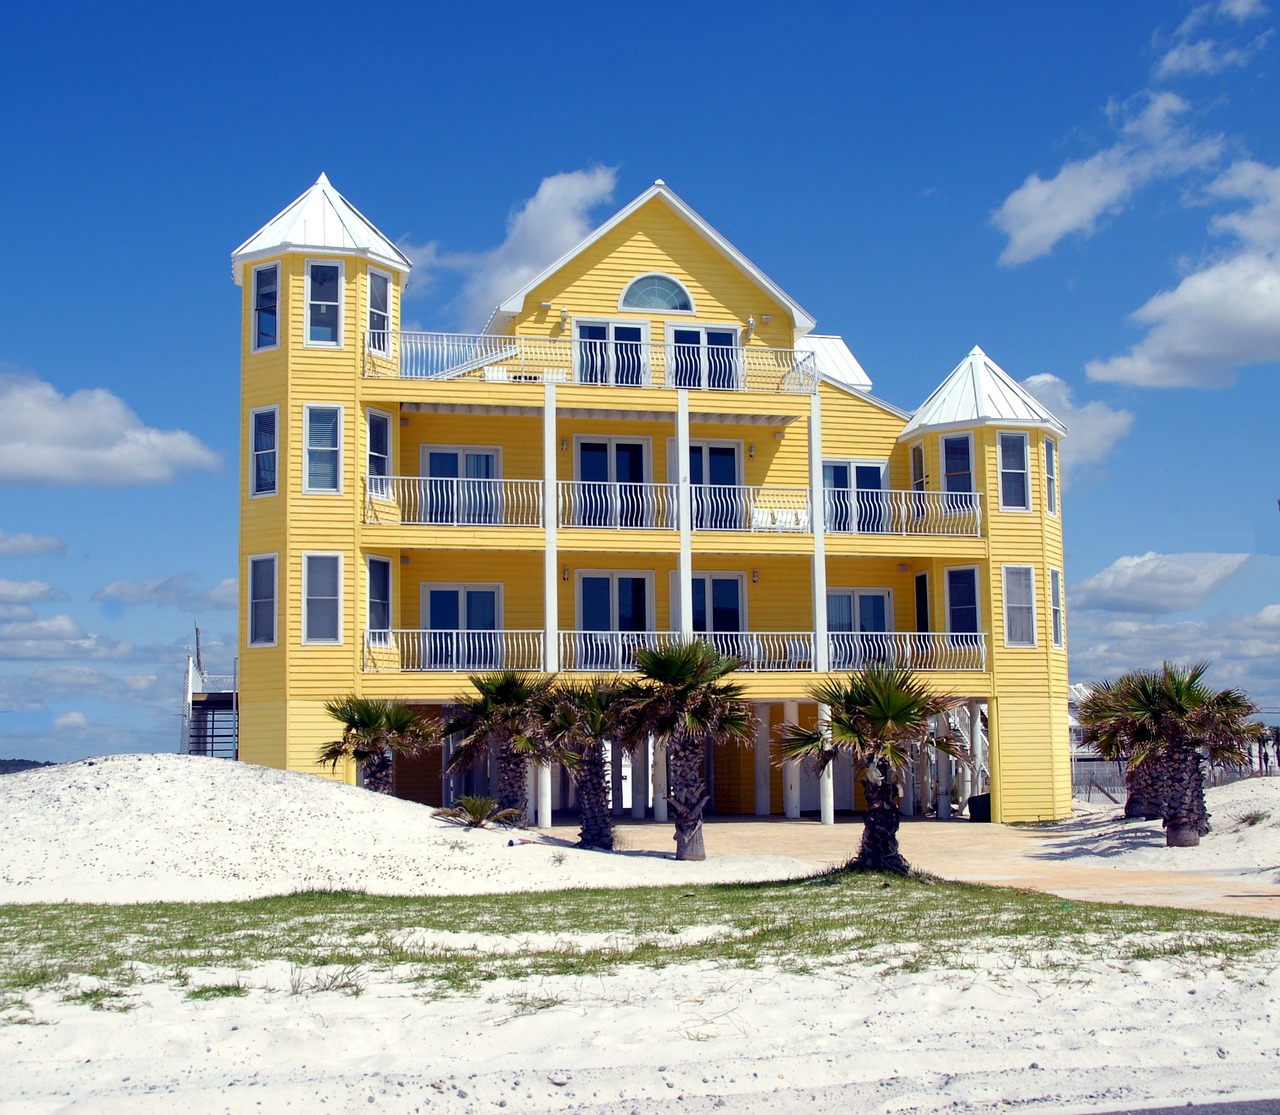
Thinking about a holiday home in the States? A place near the Florida beaches, a cabin in the Tennessee or North Carolina mountains, a condo near the Orlando parks? Owners come to us from over 75 countries, and most of them are buying from thousands of miles away. That distance is the whole insurance problem: things go wrong in an empty house, claims need handling in a different time zone, and the US insurance market works differently than the one back home. This page covers what an overseas owner of a US holiday home needs to know.
How does insuring a US holiday home work when you live abroad?
In the US, an independent agency shops your risk across many carriers and stays your single point of contact afterward, for policy changes and for claims. That matters more to an absentee owner than to anyone else: when a storm hits your Florida holiday home at 3am your time, you call one number, and the agency that placed the coverage manages the claim with the carrier while you sleep. We have done that for owners back home in the UK and across Europe. The other structural difference from many home markets: US carriers underwrite occupancy closely. A home that stands empty for months, or earns rental income, is a different risk than a lived-in house, and the policy has to say so.
Does a US policy cover the home while it stands empty?
Only if it is written for that use. A standard US homeowners policy assumes the owner lives there; long vacancies can suspend parts of the coverage, and rental activity is excluded outright on most forms. The fork is how you use the home. Kept for your own visits, it needs second-home coverage written for an absentee owner. Let to guests, what UK owners would call a holiday let and US carriers call a short-term rental, it needs short-term rental insurance, which covers the building, your liability to guests, and the rental income you lose when a covered loss closes the calendar. Annual tenants point to long-term rental coverage instead. Tell us how the home will be used and we can quote it the right way, or both ways if you are still deciding.
What catches overseas buyers by surprise?
Four things, most often. Flood is a separate policy in the US; it is not part of home coverage, and federal NFIP policies carry a 30-day wait, so it belongs in the purchase timeline, not after the keys (more on flood insurance). Coastal wind carries its own deductible, stated as a percentage of the building limit; on a $500,000 home a 5% hurricane deductible is $25,000 out of pocket, a structure many overseas buyers have never seen. US liability exposure runs higher than most home markets, which is why umbrella policies above the base coverage are common for rental owners. And in Florida specifically, the porous limestone under the state produces sinkholes; catastrophic collapse is covered on standard forms, while cosmetic sinkhole damage can need separate coverage.
Which parts of the US do you cover?
We are licensed in all 50 states, and the markets where we place the most holiday-home coverage are the ones our overseas clients buy in: Florida first, then Tennessee, North Carolina and Arizona. Each state page covers its own market’s quirks.
Fudge Insurance Can Help
Fudge Insurance is a family-owned independent agency specializing in vacation rental and holiday home insurance. We spent years exhibiting at the UK’s A Place In The Sun Live shows, so the questions overseas buyers bring are ones we have answered face to face, not just by email. Contact us and tell us about the home; we will find the policy that fits it and stay on the line after you buy.